Sign in. It’s quick, free and it’s up to you.
An account is an optional way to support the work we do. Find out more.
Sign in. It’s quick, free and it’s up to you.
An account is an optional way to support the work we do. Find out more.
LAST UPDATE | 10 Sep
THE EUROPEAN CENTRAL Bank (ECB) has raised interest rates by a quarter of a percentage point to 2.5%.
The increase comes as the bank tries to keep the surge in energy prices from the Iran war from snowballing into widespread inflation without denting economic growth.
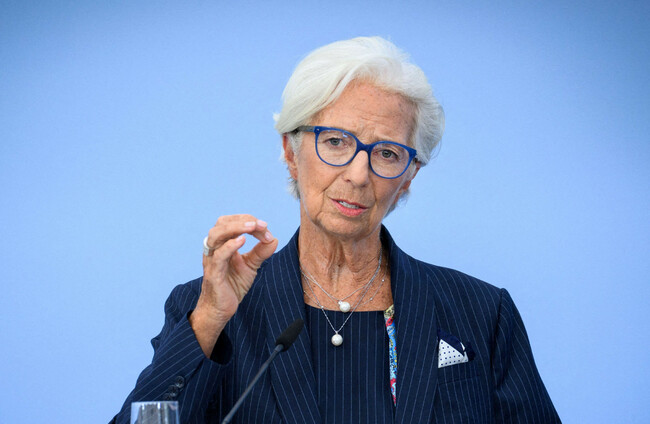
“The conflict in the Middle East continues to generate inflation pressures, and inflation is set to remain well above target for an extended period,” ECB president Christine Lagarde said.
Inflation among countries using the euro is 3.3%, which is well above the ECB’s target of 2%.
Speaking at a press conference following the announcement, Lagarde emphasised to reporters that the bank was not pre-determining what it would do in December and would instead follow a data dependent, meeting-by-meeting approach.
“The entire discussions that we had today were focused on today’s decision. We have not debated at all any kind of future path… because we are dead serious about the framework that we observe,” she said.
We don’t focus on the meeting and on the data to annoy either you or the observers. We do it because we are in this uncertainty that can change things almost overnight.
She added: “The decision we took today was a no-brainer. What we will have to do in the future will be determined at each and every meeting, but what I can tell you is that we are determined to deliver on our target.
Most analysts were in agreement that the increase was on the cards after the ECB raised its key deposit rate to 2.25% from 2% in June.
The hike will be felt first by Ireland’s more than 100,000 tracker mortgage holders, which automatically move in line with ECB rates.
Tracker mortgages are linked to the ECB’s slightly higher main refinancing rate, which will rise from 2.40% to 2.65%.
Speaking to The Journal ahead of the ECB announcement, Martina Hennessy, chief executive of broker Doddl, said that someone with €150,000 left on their tracker over 10–15 years will see their repayments jump by about €216 per year.
However, as this is the second rates increase for this year, it means that mortgage holders will now face repayments of more than €430 extra per annum.
Darragh Cassidy of price comparison website Bonkers.ie said those with variable or fixed-rate mortgages are protected for now, as their repayments won’t change until their fixed term expires.
However, lenders may increase their fixed rates for new customers in the coming weeks.
Cassidy said the big three Irish lenders – AIB, Bank of Ireland and PTSB – didn’t respond to the last ECB rate hike, keeping both their variable and fixed rates unchanged.
“This has led Irish mortgage rates to fall below the eurozone average in recent weeks, which is rare for Ireland,” he said.
“But I’m not as confident that they’ll absorb a second quarter point hike, especially for their fixed rates. And they definitely won’t absorb a third hike, which is currently a small possibility before the end of the year.”
He advised anyone thinking of switching their mortgage to do it now as they can currently avail of rates as low as 3%.
Separately, consumers may benefit from an increase on their savings and deposit rates.
Hennessy said that with mortgages being a homeowner’s single biggest monthly financial commitment, a rate increase can have a big impact, with a very significant spread between the highest and lowest mortgage rates available.
“Taking the latest new mortgage draw down level of €358,000 and looking at the difference between the highest and lowest rate on the market, savings of up to €640 per month or €7,600 per annum are possible,” the broker said.
“For a household already dealing with higher energy, food and childcare costs, that is significant.”
Economists have warned that people are going to see mortgage rates rise if they are negotiating a new loan or refinancing existing ones, meaning they will lose some of their spending power.
“People are going to see mortgage rates rise if they are negotiating a new loan or refinancing existing ones, so they lose some of their spending power,” said Frederik Ducrozet, head of strategy and macro research at Pictet Wealth Management.
This risks weighing on growth, but the ECB may feel it has little choice because the surge in fuel costs “is a real problem”, Ducrozet told AFP.
“The ECB is afraid of knock-on effects, with inflation taking root across Europe on the domestic front, for example via salary negotiations,” Ducrozet said.
But raising rates preventively “carries growing risks for the eurozone economy,” said Christophe Boucher, investment director at ABN AMRO Investment Solutions.
“If you expect rates to raise even more, and if the yields on the long-term debt of France and other European countries continue to climb, it tightens monetary conditions even more than central bank hikes alone,” Ducrozet said.
By raising the interest dates, it’s likely to put a damper on spending plans for both households and businesses who are faced with higher mortgage costs.
With reporting from Jane Moore

To embed this post, copy the code below on your site



have your say